Ollo Credit Card Mobile App

Screenshots
Details
- Rating
- 184.00 reviews
- Version
- 4.49.11
- Developer
- Merrick Bank
Analysis by Norviv
If you have an Ollo credit card and want a simpler way to keep an eye on it from your phone, Ollo Credit Card is built for that everyday job. I approached it as a first-time cardholder would: install the free finance app, sign in, look for the information that matters, and try to make account management feel less like a chore. The result is a focused mobile companion from Merrick Bank rather than a broad money-management platform.
That narrow purpose is both its main strength and its biggest limitation. I like that the app is aimed at one card relationship instead of trying to combine bank accounts, investments, budgeting tools, and unrelated financial products. At the same time, anyone hoping for a complete household-finance dashboard should look elsewhere. This review follows the path I would recommend to a new user, from the first launch through the point where the app becomes useful in a normal week.
What to expect from the mobile card experience
The first thing to understand is the app’s role. Its store summary presents it as a way to manage an Ollo credit card, and that description is a better guide than expecting a general-purpose banking app. I would use it to check the card account, review activity, stay aware of payment responsibilities, and handle routine account tasks from a phone. The value comes from having the card relationship close at hand, not from a large collection of financial planning tools.
That focus makes the interface easier to approach when you are new to mobile account management. You do not need to learn a complicated budgeting system before getting a useful result. My advice is to judge the app by a practical question: can it help you answer “What is happening with my card right now?” quickly and confidently? For an Ollo cardholder, that is the right standard.
The app is free, carries an Everyone content rating, and works on Android devices running version 6.0 or newer. It has reached over one hundred thousand installs, with a 3.7 average from 323 ratings and 184 written reviews. Those figures suggest a real user base, but also a mixed experience rather than universal approval. I would treat that as a reason to keep expectations realistic: the app can be useful without being perfect.
It is currently listed as version 4.49.11, and the developer is Merrick Bank. Because this is a financial account tool, I would install it only from the official app store and keep the phone’s operating system reasonably current. The free price removes one barrier to trying it, but the app does not replace the need to understand your card agreement, payment deadlines, or spending decisions.
Who will get the most from it
I think it suits someone who already has an Ollo card and wants a direct way to check the account while away from a computer. It is especially practical for people who make purchases throughout the week and prefer to verify activity from a phone rather than wait for a statement. It can also help a new cardholder build a habit of checking the account before making another purchase.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would be less enthusiastic about it for someone who wants one place to manage several cards from different issuers. A dedicated issuer app normally works best when your main account is with that issuer. If your priority is comparing balances across multiple providers, categorizing every expense, or viewing a complete net-worth picture, a broader personal-finance service may be a better fit.
Why a focused app can be better than a general finance tool
There is a useful trade-off here. General finance apps can show a wider picture, but they may require connected accounts, extra organization, and more screens between you and the card detail you actually need. A card-specific app can be quicker for a narrow task. When I want to confirm whether a card transaction has appeared or check the account before a purchase, I would rather start with the issuer’s own tool than search through an unrelated dashboard.
The opposite is also true. A focused app may leave you switching between services when you want to plan a monthly budget or compare spending across cards. That is not a flaw unique to this product; it is the natural cost of keeping the experience centered on one Ollo account. Knowing that before installing it prevents disappointment later.
From installation to the first useful result
I found the first useful step is to treat setup as an account check, not a race through sign-in screens. In this section, I’d focus on confirming that you have reached the right card account and learning which details are worth checking first. That gives the next section a practical starting point: what can make that first visit less straightforward than expected.
Start with a calm, deliberate setup
For a first launch, I recommend having your Ollo card and the account details you normally use for secure sign-in nearby. The goal is not to rush through the opening screens. Read each prompt, use a password you do not reuse elsewhere, and avoid entering account information while connected to an untrusted public network. These are simple steps, but they matter more in a finance app than in a casual shopping or entertainment app.
If the app asks you to confirm your identity or accept account terms, take a moment to check that the information relates to your own Ollo card. A first-time user can easily assume that installation alone creates access; in practice, the useful part begins only after the correct account has been connected through the app’s sign-in process. If something does not match, I would stop and verify the account rather than repeatedly guessing credentials.
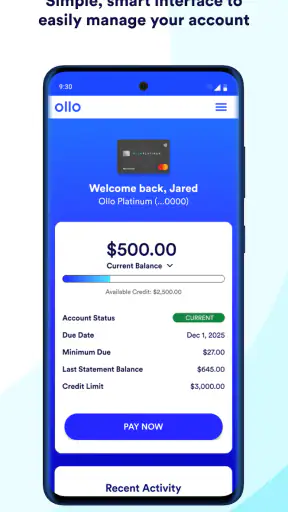
After signing in, spend a minute learning the opening screen instead of immediately tapping through every option. Look for the areas that answer three basic questions: what is the current account position, what activity has appeared, and what action needs attention next? This small orientation step saves time later because you will know where to return when you are checking the card in a hurry.
Your first successful action should be a simple account check
The first meaningful success I would aim for is not a complicated account change. It is confirming that the app shows the expected card account and that the recent information makes sense. Compare a familiar purchase or account detail with what you already know. This gives you confidence that you are looking at the right account and teaches you how the app presents card activity.
A realistic example is a grocery trip on the way home. After paying, I would open the app later that day, sign in, and check whether the purchase is visible or whether the account information has changed in a way I recognize. I would not assume that every transaction appears instantly or that a pending item has the same meaning as a completed one. The useful habit is checking the account without treating an early display as the final word.
That workflow has an overlooked benefit: it turns the app into a personal verification point. If a purchase looks unfamiliar, you can investigate while the details are still fresh instead of discovering it much later. If the information looks correct, you can close the app and move on. The app is most valuable when it supports this quick, repeatable check rather than encouraging constant monitoring.
Use the app before, not only after, a purchase
Many people open a card app only after spending. I find it more useful to check beforehand when a purchase is unusually large or when I am unsure how much room remains in the account. That does not turn the app into a budgeting system, but it gives me a current reference point before committing to a charge.
For a first-time user, this is a good second step after the initial account check: open the app before a planned purchase, review the account information, and decide whether the purchase fits your own plan. The app can provide visibility, but it cannot make the financial decision for you. I would never treat an available amount shown in an app as permission to spend beyond what I can comfortably repay.
Build a payment-check routine
Another practical use is making the app part of a payment routine. I would choose a regular day to review the account, look at recent activity, and confirm what needs attention. The exact schedule should match your own payment obligations; the important point is consistency. A quick review is easier to maintain than waiting until a deadline feels urgent.
Keep your statement and account terms as the final authority for obligations. The app is a convenient way to access account information, but a mobile screen should not replace reading the details that govern your card. This distinction is especially important for a new user who may confuse a visible balance, a pending transaction, and the amount required by a statement.
Where first-time users may feel confused
A first login can feel unclear when you are unsure whether a prompt is part of sign-in, identity confirmation, or a later account task. I’d slow down and compare each request with the account information you already use, rather than guessing or repeating entries. The next section looks at how to turn a successful login into a small routine that helps without encouraging constant checking.
Account information is not the same as a spending plan
The most common misunderstanding I would expect is assuming that seeing a balance means the app is tracking a complete budget. It is not the same thing as knowing how much you can safely spend across rent, groceries, bills, and other cards. Ollo Credit Card can help you see the card relationship, but you still need your own method for planning money outside that account.
If you use several cards, write down or track the combined picture somewhere reliable. The dedicated app can remain the place for Ollo-specific checks while another tool handles the wider household view. That split is often more sensible than forcing one app to do everything.
Pending activity deserves patience
Card activity can change as transactions move through processing. A purchase that appears one way at first may later settle differently, and a merchant’s displayed description may not be as familiar as the name on a receipt. I would compare the amount, timing, and merchant context before assuming that an unfamiliar line is fraudulent or incorrect.
That does not mean ignoring a transaction that genuinely looks wrong. It means avoiding two opposite mistakes: panicking over a normal processing difference or dismissing a real problem because the amount seems small. The app makes checking easier, but good judgment still matters. Keep receipts for unusual purchases until the activity is clear.
Sign-in friction is a security feature as well as an inconvenience
Finance apps can feel slower than social or shopping apps because account access has higher consequences. If you are asked to authenticate again, I would see that as part of protecting the account rather than automatically treating it as a defect. The trade-off is obvious: stronger access controls can interrupt a quick check, but removing all friction would not be a sensible goal for a card-management tool.
If sign-in fails, check the basics once: confirm the credentials, verify the network, and make sure you are using the correct account information. Repeated guessing is more likely to create frustration than solve the problem. When the app is unavailable or an urgent account issue needs attention, use the support route associated with your card rather than relying on repeated app attempts.
Do not confuse convenience with complete account control
A mobile app can make routine management easier, but not every card question belongs in the app. Complex disputes, identity concerns, or questions about account terms may require direct assistance. I would use the app for visibility and ordinary account handling, then move to the appropriate support channel when the situation needs a detailed explanation or formal resolution.
This is also why I would avoid sharing screenshots of account details casually. A screenshot can include information that should remain private. If you need help from someone you trust, remove sensitive details first and never share passwords or security codes.
Small habits that make the app more useful
I get more value from a card app when I open it with a specific question instead of browsing every screen. Here, I’d cover a few low-effort habits for checking Ollo activity around purchases, returns, and planned spending, while keeping the app in its proper role. That leads naturally to the next section’s practical routines and the situations where a wider finance tool may still be useful.
Use a three-point review instead of aimless browsing
When I open the app, I would follow the same short sequence: check the account position, scan recent activity, and identify the next action. This is more effective than opening every screen without a purpose. It also gives a first-time user a repeatable workflow that remains useful after the novelty of installation disappears.
The first point tells me where the account stands. The second helps me catch activity I recognize or need to investigate. The third keeps the check connected to a decision, such as reviewing a payment responsibility or waiting for a transaction to finish processing. This structure turns a basic card app into a practical routine without pretending it is a full financial planner.
Check after unusual events
Normal purchases do not require constant attention, but unusual events deserve a closer look. I would check after a large purchase, a return, a subscription change, or a trip where the card was used in several places. The point is not to refresh repeatedly; it is to create a clear moment when you reconcile what happened with what the account shows.
Returns are a particularly good example. I would keep the merchant receipt, note when the return was made, and use the app to watch for the account activity to reflect it. If the result does not match the documentation, I would have useful details ready when seeking help. This is a more reliable workflow than relying on memory.
Keep the app in its proper place on a shared device
If other people can use your phone, I would pay attention to device security before relying on a finance app. Use the phone’s own lock, avoid leaving the account open, and sign out or secure the session when appropriate. The app’s convenience is only helpful if access to the device is controlled.
I would also avoid installing it on a device that no longer receives security updates. The minimum operating-system requirement is Android 6.0, but meeting a technical requirement is not the same as having a well-protected device. For financial information, the phone’s overall security condition matters as much as compatibility.
Where it fits among the usual alternatives
Compared with a desktop account portal, the mobile app is more convenient for quick checks because the phone is usually nearby. A website may still feel better for a longer session, especially if you prefer a larger screen or need to read several pieces of account information at once. I would use the mobile app for speed and the browser experience, when available through the issuer, for situations where a wider layout is more comfortable.
Compared with a general budgeting app, this tool should feel more direct for Ollo-specific information but less complete for overall planning. Budgeting software can help organize categories and multiple accounts, while a card app keeps attention on the issuer relationship. Neither replaces the other for every user. If your main question is “What is happening with my Ollo card?”, the dedicated app is the logical starting point. If your question is “Where did all my money go this month?”, you need a broader system.
Compared with paper statements or waiting for email reminders, a phone-based account check can make information easier to reach. However, convenience can encourage passive behavior. I would not install the app and assume the problem of managing credit is solved. The best result comes from pairing quick checks with a realistic repayment plan and careful attention to account terms.
My recommendation after using it as a new cardholder
I would recommend Ollo Credit Card to an existing Ollo cardholder who wants a free, issuer-specific way to stay connected with the account. Its strongest quality is focus: it keeps the first-time path understandable, supports quick checks, and can become part of a sensible routine after purchases or before planned spending. The 3.7 average indicates that the experience is not flawless for everyone, so I would keep a little patience for sign-in or account-display friction.
I would skip it as my primary finance app if I needed multi-card management, detailed budgeting, investment tracking, or a complete household overview. I would also avoid treating it as a substitute for statements, card terms, or direct support when a problem is serious. Those are not reasons for an Ollo cardholder to dismiss it; they are boundaries that make its purpose clearer.
My suggested path is simple. Install the free app on a secure compatible device, sign in carefully, confirm that the account information looks familiar, and make one ordinary account check after a purchase. Then use the three-point review—account position, recent activity, next action—whenever you need a quick update. The first meaningful success is not merely opening the app; it is knowing what your Ollo account requires from you today.
That is where this mobile finance tool earns its place. It will not organize every part of your financial life, and it should not be judged as though it were designed to do so. For the right user, it offers a straightforward bridge between having an Ollo card and actively keeping track of it. I would keep it installed if that focused access matches the way you manage credit, while using a broader tool or the issuer’s other support options whenever the question extends beyond the card itself.
Frequently Asked Questions
01What is the Ollo Credit Card mobile app used for?
The Ollo Credit Card mobile app is designed to help cardholders manage their account from an Android or iOS device. After signing in, users can generally review available credit, check recent and pending transactions, view statements, make payments, monitor account activity, and update selected personal settings. It provides a convenient alternative to accessing the account through a web browser, although available features may depend on the cardholder’s account and Ollo’s current services.
02How do I log in to the Ollo Credit Card app for the first time?
To use the Ollo Credit Card app, you normally need an active Ollo card account and the login credentials associated with it. New users may have to complete registration through the official Ollo enrollment process before signing in. The app may request identity verification, such as personal information or a security code. Always download the application from an official store and avoid entering account details into unofficial copies or suspicious links.
03Can I pay my Ollo Credit Card bill through the app?
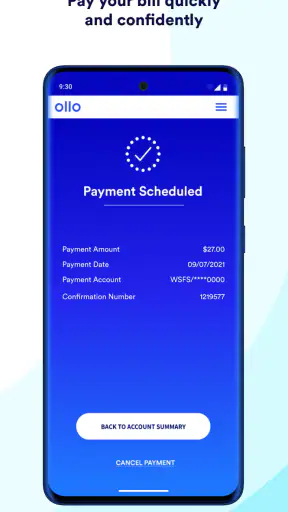
The app is intended to make account payments more convenient, allowing eligible cardholders to review their balance and submit a payment from a linked bank account or another supported payment method. Before confirming, carefully check the payment amount, scheduled date, and funding account. Processing times can vary, so users should not wait until the due date if they want to avoid late-payment problems or possible returned-payment fees.
04Does the Ollo app show transactions, statements, and available credit?
Yes, one of the app’s main purposes is to provide a current overview of your Ollo Credit Card account. Depending on your account type and the version of the app, you may be able to see posted and pending transactions, payment history, statement information, minimum payment requirements, total balance, and available credit. Pending charges may change before posting, so the displayed available credit should be treated as an estimate until transactions settle.
05Is the Ollo Credit Card app safe, and what should I do if I notice suspicious activity?
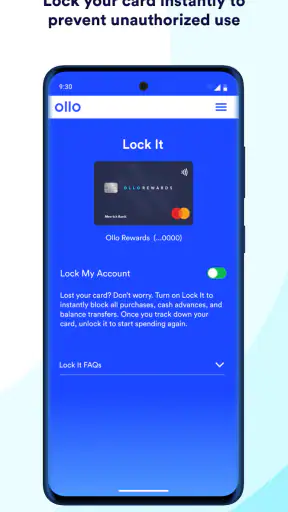
Using the official Ollo Credit Card app can be safer than managing your account through unknown websites, provided that you install it from Google Play or the Apple App Store and keep your device updated. Use a strong, private password and never share verification codes. If you see an unfamiliar transaction, receive a suspicious login alert, or lose your phone, contact Ollo through official customer-service channels immediately and secure your device and account.


